Tax and SARS compliance, handled end to end
Every return that falls due gets filed on time, and we take the SARS correspondence directly as your registered representative. VAT, income tax, provisional tax, tax clearance, verifications and disputes.
Tax and SARS compliance for South African businesses
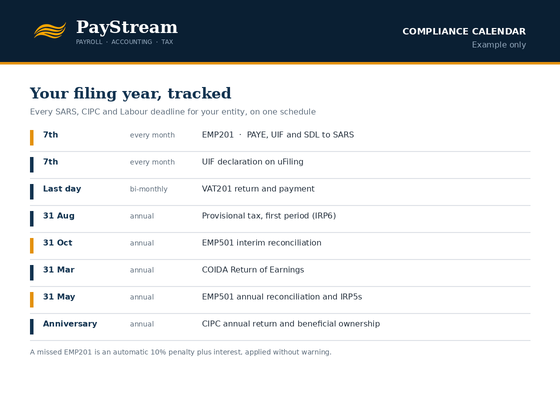
Tax compliance is not one event a year. For a registered company it is a rolling calendar of monthly, twice yearly and annual obligations, and SARS applies penalties automatically when one is missed. PayStream keeps that calendar for you, files what falls due, and takes the correspondence directly so a SARS letter is not something you have to interpret on your own.
We act as your registered representative on eFiling. That means verifications, audit letters, statements of account and requests for supporting documents come to us, get dealt with, and reach you as a short summary of what happened rather than a scanned PDF you were not expecting.
The returns we file
- VAT201. Monthly or bi-monthly depending on your category, reconciled to the ledger before submission rather than submitted from a software button and hoped for.
- Company income tax (ITR14). The annual return, with the tax computation and supporting schedules that back up the numbers if SARS asks.
- Provisional tax (IRP6). The first period by end August, the second by end February and a voluntary third top up where it saves interest.
- Personal income tax (ITR12). For directors, sole proprietors and individuals with rental, investment or foreign income.
- Payroll taxes. EMP201 monthly and EMP501 twice a year, covered in full under payroll outsourcing.
- Dividends tax and DTR returns where a company declares dividends.
VAT registration and the R1 million question
VAT registration becomes compulsory once your taxable supplies exceed R1 million in any consecutive twelve month period, or where you have a written contract that will take you past it in the next twelve months. Voluntary registration is available from R50,000 of taxable supplies, and it can be worth doing early if your customers are themselves VAT registered businesses and your input VAT is meaningful.
It is often worth not doing, if you sell to the public. Registering adds 15 percent to your price to a consumer who cannot claim it back, and adds a permanent monthly filing obligation. We will tell you which side of that line you are on before you register, not after.
Tax clearance and the TCS PIN
The Tax Compliance Status system replaced the old paper tax clearance certificate. You share a PIN, and whoever you give it to sees your live compliance status at any moment they check it. That is the part businesses underestimate: it is not a certificate you obtain once for a tender, it is a live status that can turn non compliant the day an EMP201 goes unfiled.
Staying permanently tender ready means every registered tax type is filed and every account is either paid or under an approved arrangement. We manage the underlying compliance and then issue the PIN when you need it, rather than starting a two week scramble the week a tender closes. Full detail on our tax clearance page.
SARS verifications, audits and disputes
Being selected for verification is routine and is not an accusation. It usually means a figure on a return did not match third party data SARS already holds. What matters is responding inside the deadline with the right supporting documents, in the format SARS expects.
Where an assessment is wrong we lodge a formal objection through the dispute process, and where penalties and interest have accumulated we apply for remission on the grounds available, which most commonly are first incidence, reasonable cause or circumstances beyond the taxpayer's control. Many businesses simply pay penalties that could have been remitted, because nobody told them the process existed.
Tax planning that is legal and boring
There is a large difference between structuring a business efficiently and the schemes that end badly. We stay firmly on the first side of that line: correct use of the small business corporation regime where you qualify, section 12E accelerated allowances on qualifying assets, section 11(e) wear and tear, the section 13sex allowance on qualifying new residential units, home office deductions where the requirements are genuinely met, and getting the director salary versus dividend mix right for your circumstances.
None of that is exotic. It is the ordinary relief the Income Tax Act already provides, applied consistently, which over five years is worth considerably more than any clever idea.
Scope
What is included
VAT registration and returns
Registration where compulsory or beneficial, then VAT201 filed on your cycle and reconciled to the ledger.
Income tax returns
ITR14 for companies and ITR12 for individuals, with the computation and schedules behind them.
Provisional tax
IRP6 first and second period, estimated properly so you avoid the underestimation penalty.
Tax clearance
TCS PIN issued and kept live, so a tender deadline is never the thing that catches you out.
SARS correspondence
Verifications, audits, statements of account and requests for documents handled as your representative.
Objections and remissions
Formal disputes against incorrect assessments, and penalty and interest remission applications.
In detail
Tax services in detail
These pages go into the returns and processes that come up most often for South African business owners.
VAT returns (VAT201)
Registration, monthly or bi-monthly returns, and VAT control account reconciliation.
Read more ServiceTax clearance (TCS PIN)
Getting compliant, getting the PIN, and staying tender ready all year.
Read more ServiceCIPC annual returns
The company law side of compliance, and the deregistration risk if it slips.
Read moreQuestions
Tax and SARS questions, answered
When must a South African business register for VAT?
Registration is compulsory once taxable supplies exceed R1 million in any consecutive twelve month period, or where a written contract commits you to exceeding it within the next twelve months. Voluntary registration is possible from R50,000 of taxable supplies in the past twelve months. Compulsory registration must be applied for within 21 business days of exceeding the threshold.
What are the provisional tax deadlines?
For a February year end, the first provisional return (IRP6) is due by 31 August and the second by 28 or 29 February. An optional third top up payment can be made by end September to limit interest. Companies with other year ends follow the same pattern relative to their own financial year.
What happens if I file a SARS return late?
Penalties differ by tax type. Late EMP201 attracts an automatic 10 percent penalty plus interest. Late income tax returns attract a monthly administrative penalty that runs per month outstanding and escalates with taxable income. Late VAT attracts a 10 percent penalty plus interest. Most of these can be applied for remission where there is reasonable cause, but only if someone applies.
Can PayStream deal with SARS on my behalf?
Yes. We are appointed as your registered representative on eFiling, which lets us receive and respond to SARS correspondence, submit returns, request statements of account, lodge objections and negotiate payment arrangements. You are copied on the outcome of everything.
I have not filed returns in years. Can that be fixed?
Yes, and it is more common than people assume. We establish what is actually outstanding by pulling your full SARS statement of account, file the returns in the correct sequence, apply for remission of the penalties that qualify, and arrange a payment plan if there is a balance. Voluntary disclosure is available in the right circumstances and gives better outcomes than waiting to be found.
Do you handle personal tax for directors as well as the company?
Yes. In an owner managed business the two are connected, and getting the salary, dividend and loan account mix right requires looking at both together. Director personal returns are normally included in the company plan.
What is a TCS PIN and how long does it take to get one?
The Tax Compliance Status PIN is what replaced the old tax clearance certificate. Where all tax types are filed and paid, the PIN issues through eFiling within about 24 to 48 hours. Where something is outstanding it can take weeks, because the underlying non compliance has to be fixed first. That is the argument for staying compliant continuously rather than at tender time.
Let's put a number on it.
Tell us your headcount and what you need covered. You get a written, fixed monthly quote within 48 hours. No obligation, no sales pressure.